

Regional banking company Byline Bancorp (NYSE:BY) will be announcing earnings results tomorrow after the bell. Here’s what to expect.
Byline Bancorp beat analysts’ revenue expectations last quarter, reporting revenues of $117.7 million, up 6.6% year on year. It was a strong quarter for the company, with a beat of analysts’ EPS estimates and net interest income in line with analysts’ estimates.
Is Byline Bancorp a buy or sell going into earnings? Read our full analysis here, it’s free for active Edge members.
This quarter, the market is expecting Byline Bancorp’s revenue to be flat year on year, slowing from the 13.6% increase it recorded in the same quarter last year.
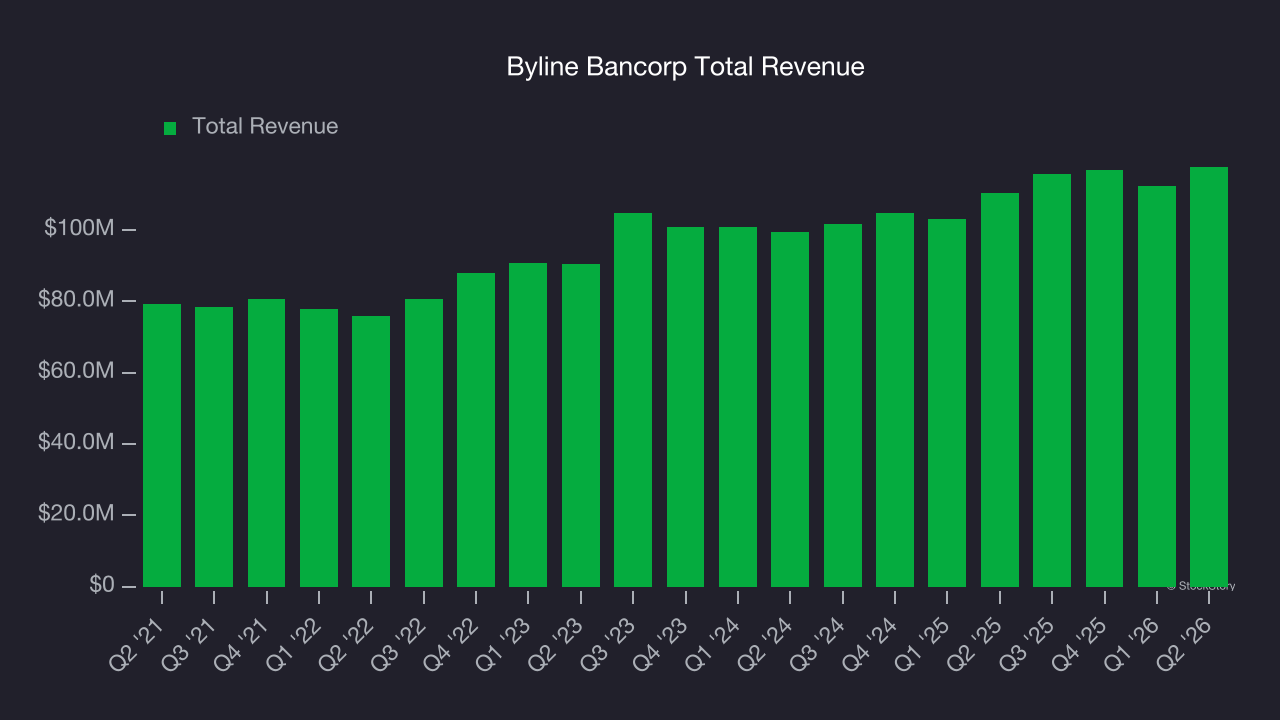
Analysts covering the company have generally reconfirmed their estimates over the last 30 days, suggesting they anticipate the business will stay the course heading into earnings. Byline Bancorp rarely misses Wall Street’s revenue estimates.
Looking at Byline Bancorp’s peers in the regional banks segment, some have already reported their Q3 results, giving us a hint as to what we can expect. QCR Holdings’s revenues decreased 11.7% year on year, missing analysts’ expectations by 8.9%, and Washington Trust Bancorp reported revenues up 15%, topping estimates by 4.1%. Washington Trust Bancorp traded up 4% following the results.
Read our full analysis of QCR Holdings’s results here and Washington Trust Bancorp’s results here.
Investors in the regional banks segment have had fairly steady hands going into earnings, with share prices down 1.9% on average over the last month. Byline Bancorp is up 2.5% during the same time and is heading into earnings with an average analyst price target of $43.20 (compared to the current share price of $37.92).
ONE MORE THING: The $21 AI Application Stock Wall Street Forgot. While Wall Street obsesses over who’s building AI, one company is already using it to print money. And nobody’s paying attention.
AI chip stocks trade at ridiculous valuations. This company processes a trillion consumer signals monthly using AI and trades at a third of the price. The gap won’t last. The institutions will figure it out. You need to see this first. Read the FREE Report Before They Notice.