

Over the last six months, Conagra’s shares have sunk to $14.04, producing a disappointing 5.4% loss - a stark contrast to the S&P 500’s 7.7% gain. This may have investors wondering how to approach the situation.
Is there a buying opportunity in Conagra, or does it present a risk to your portfolio? See what our analysts have to say in our full research report, it’s free.
Why Do We Think Conagra Will Underperform?
Even though the stock has become cheaper, we’re cautious about Conagra. Here are three reasons you should be careful with CAG, plus one stock we’d rather own.
1. Demand Slipping as Sales Volumes Decline
Revenue growth can be broken down into changes in price and volume (the number of units sold). While both are important, volume is the lifeblood of a successful staples business as there’s a ceiling to what consumers will pay for everyday goods; they can always trade down to non-branded products if the branded versions are too expensive.
Conagra’s average quarterly sales volumes have shrunk by 1.6% over the last two years. This decrease isn’t ideal because the quantity demanded for consumer staples products is typically stable. 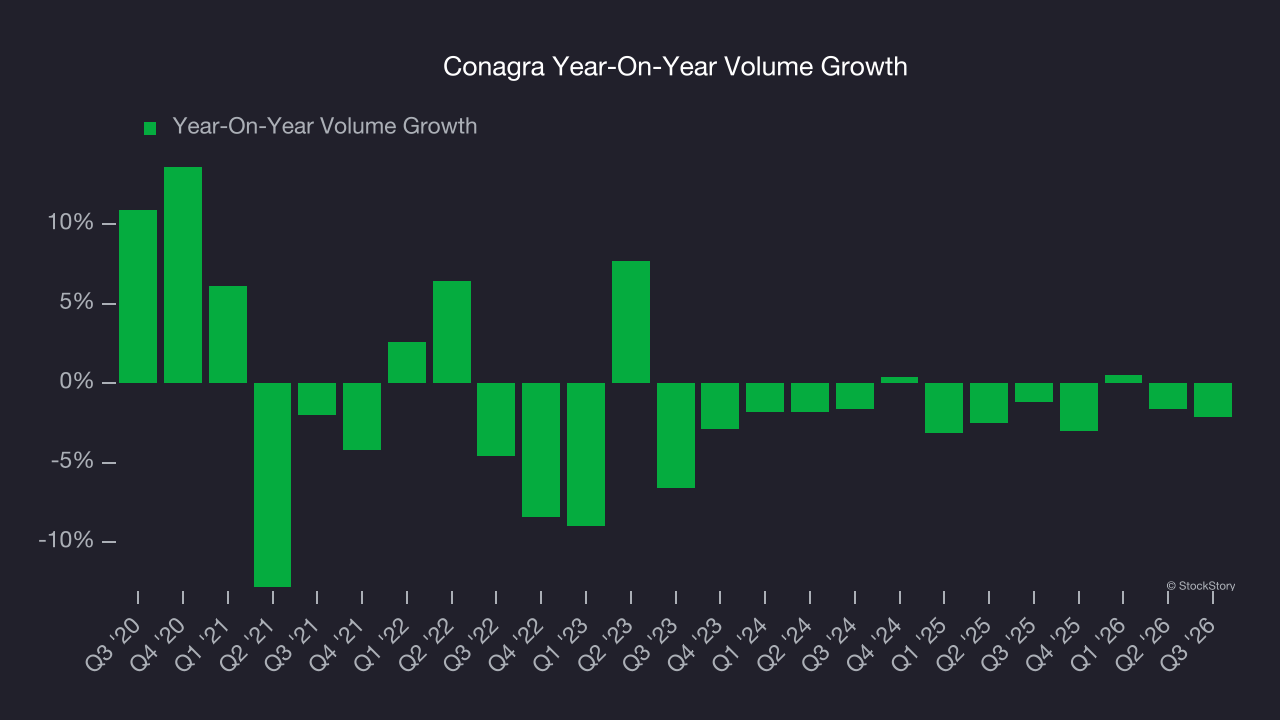
2. Shrinking Operating Margin
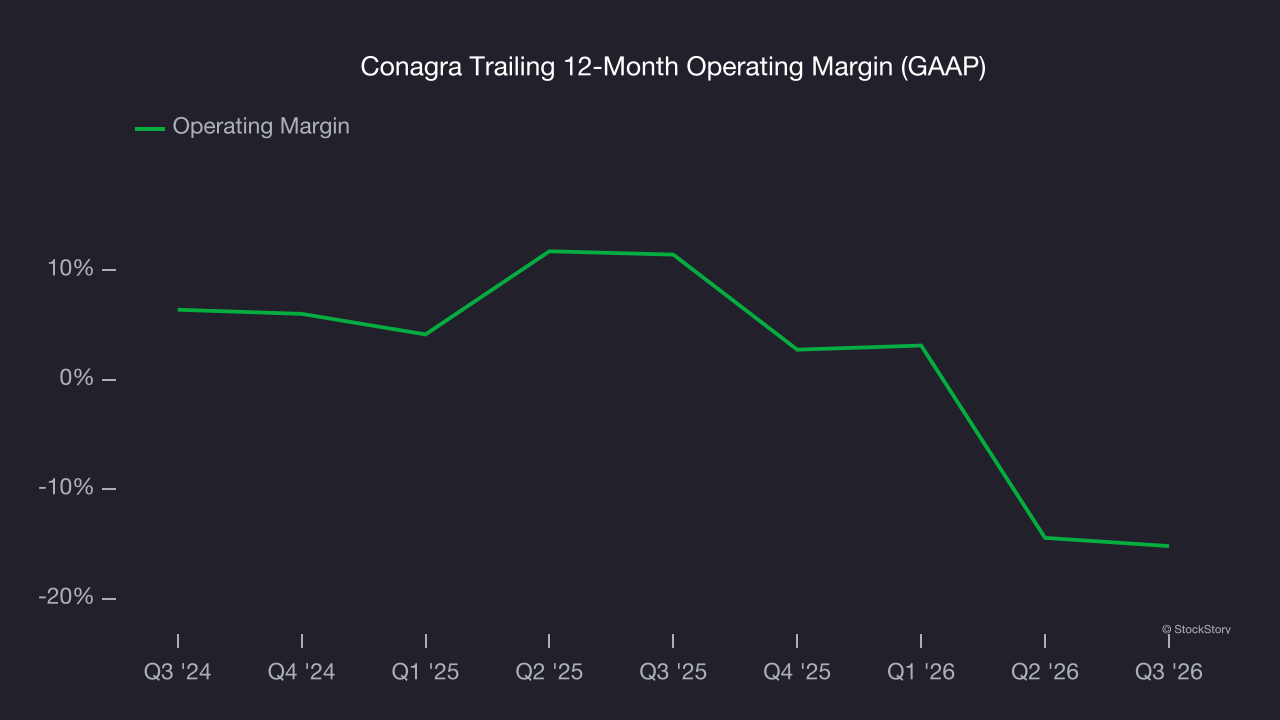
Operating margin is a key measure of profitability. Think of it as net income - the bottom line - excluding the impact of taxes and interest on debt, which are less connected to business fundamentals.
Analyzing the trend in its profitability, Conagra’s operating margin decreased by 26.6 percentage points over the last year. Conagra’s performance was poor no matter how you look at it - it shows that costs were rising and it couldn’t pass them onto its customers. Its operating margin for the trailing 12 months was negative 15.2%.
3. EPS Trending Down
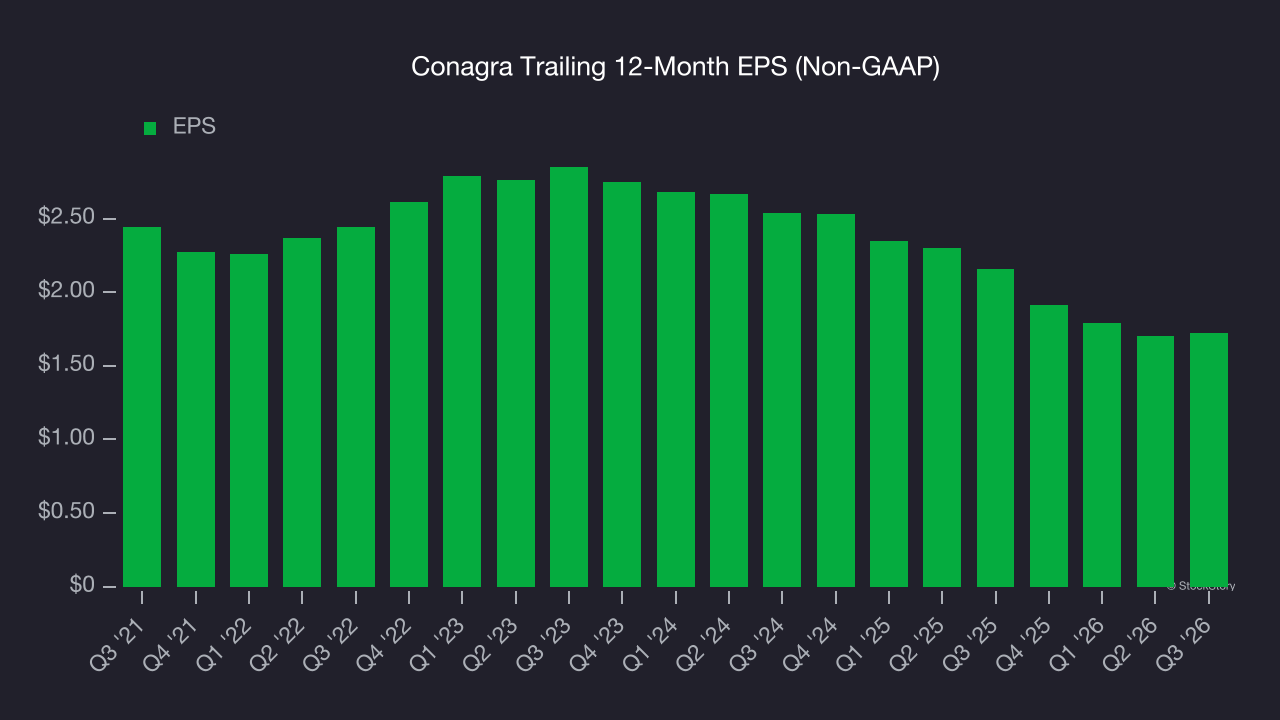
We track the long-term change in earnings per share (EPS) because it highlights whether a company’s growth is profitable.
Sadly for Conagra, its EPS declined by 15.5% annually over the last three years, more than its revenue. This tells us the company struggled because its fixed cost base made it difficult to adjust to shrinking demand.
Final Judgment
Conagra falls short of our quality standards. Following the recent decline, the stock trades at 10.1× forward P/E (or $14.04 per share). This valuation multiple is fair, but we don’t have much confidence in the company. There are better stocks to buy right now. We’d suggest looking at the most dominant software business in the world.
Stocks We Would Buy Instead of Conagra
WHILE YOU’RE HERE: Top 9 Market-Beating Stocks. The best stocks don’t just beat the market once. They do it again. And again. Robust revenue growth, rising free cash flow, returns on capital that leave their competition in the dust. The market has already rewarded these businesses.
But our AI platform says the party isn’t over. Find out which 9 stocks made the cut this week — FREE. Get Our Top 9 Market-Beating Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-micro-cap company Tecnoglass (+1,552% between June 2020 and June 2025). Find your next big winner with StockStory today.